Unconventional Rate-Transient Analysis
Description
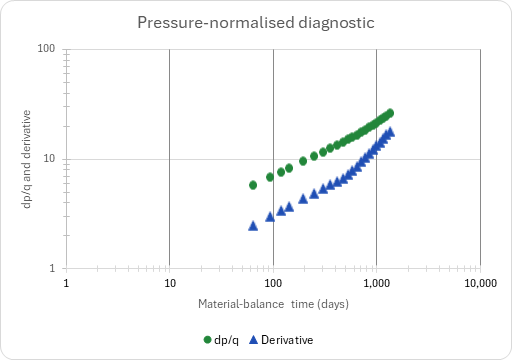
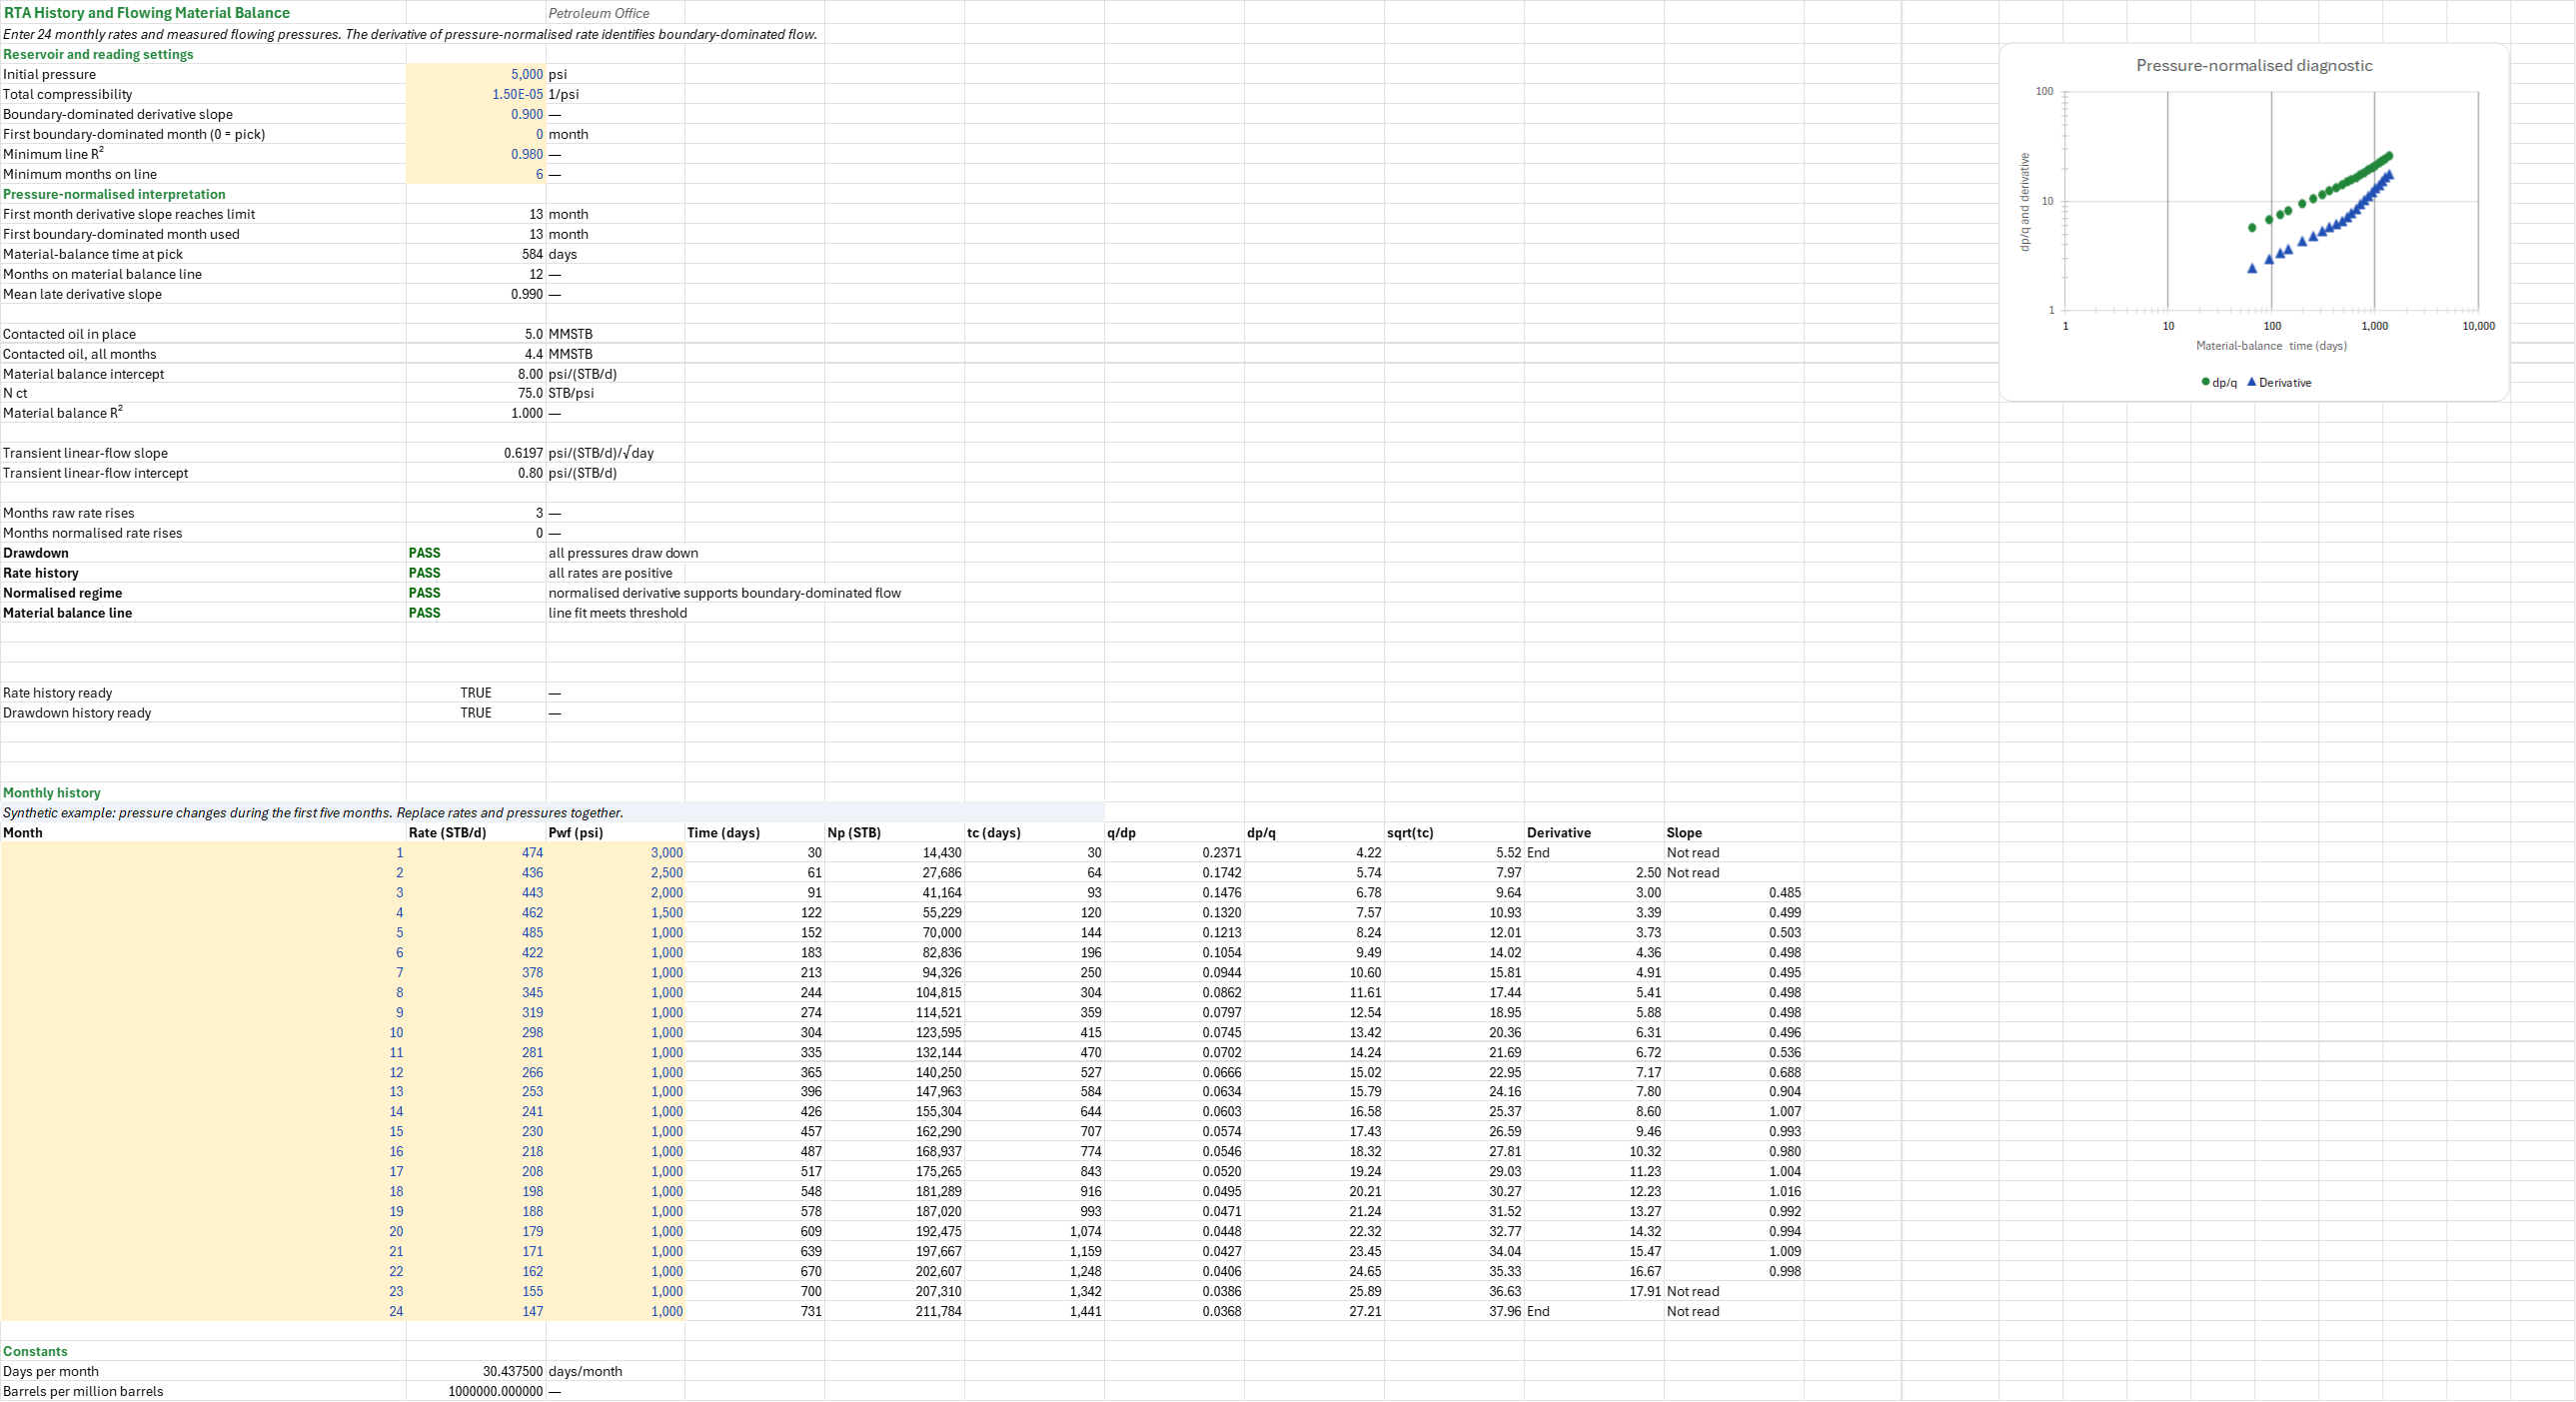
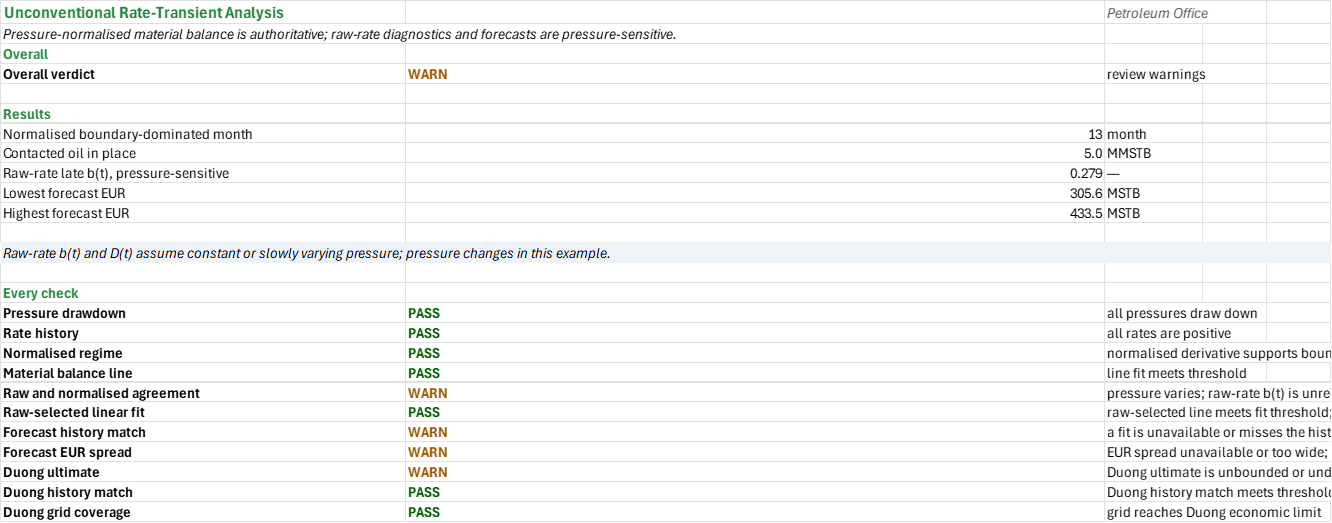
Has this tight-oil well reached boundary-dominated flow, how much oil does it contact, and what will it recover? You enter 24 monthly rates and flowing bottomhole pressures, the initial pressure and total compressibility. You read off a pressure-normalised rate-transient diagnostic, the contacted oil in place from flowing material balance, raw-rate decline diagnostics, and four empirical decline forecasts to one economic limit with their EURs. Time is in months for decline fits and days for material-balance time; rates are STB/d.
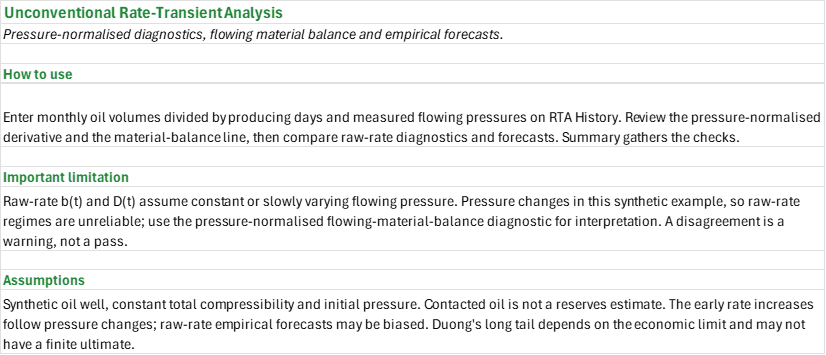
How to use it: On the RTA History sheet, enter monthly oil volume divided by producing days, together with representative measured flowing bottomhole pressure for the same period. Every rate must be positive and every pressure must be numeric, non-negative and below positive initial pressure. An invalid or missing rate disables the history-based diagnostics and forecasts; invalid drawdown disables pressure-normalised results. Use independently justified initial pressure, total compressibility and economic limit. Review the Summary failures, shut-ins, rate changes and measurement quality; the Summary shows every check.
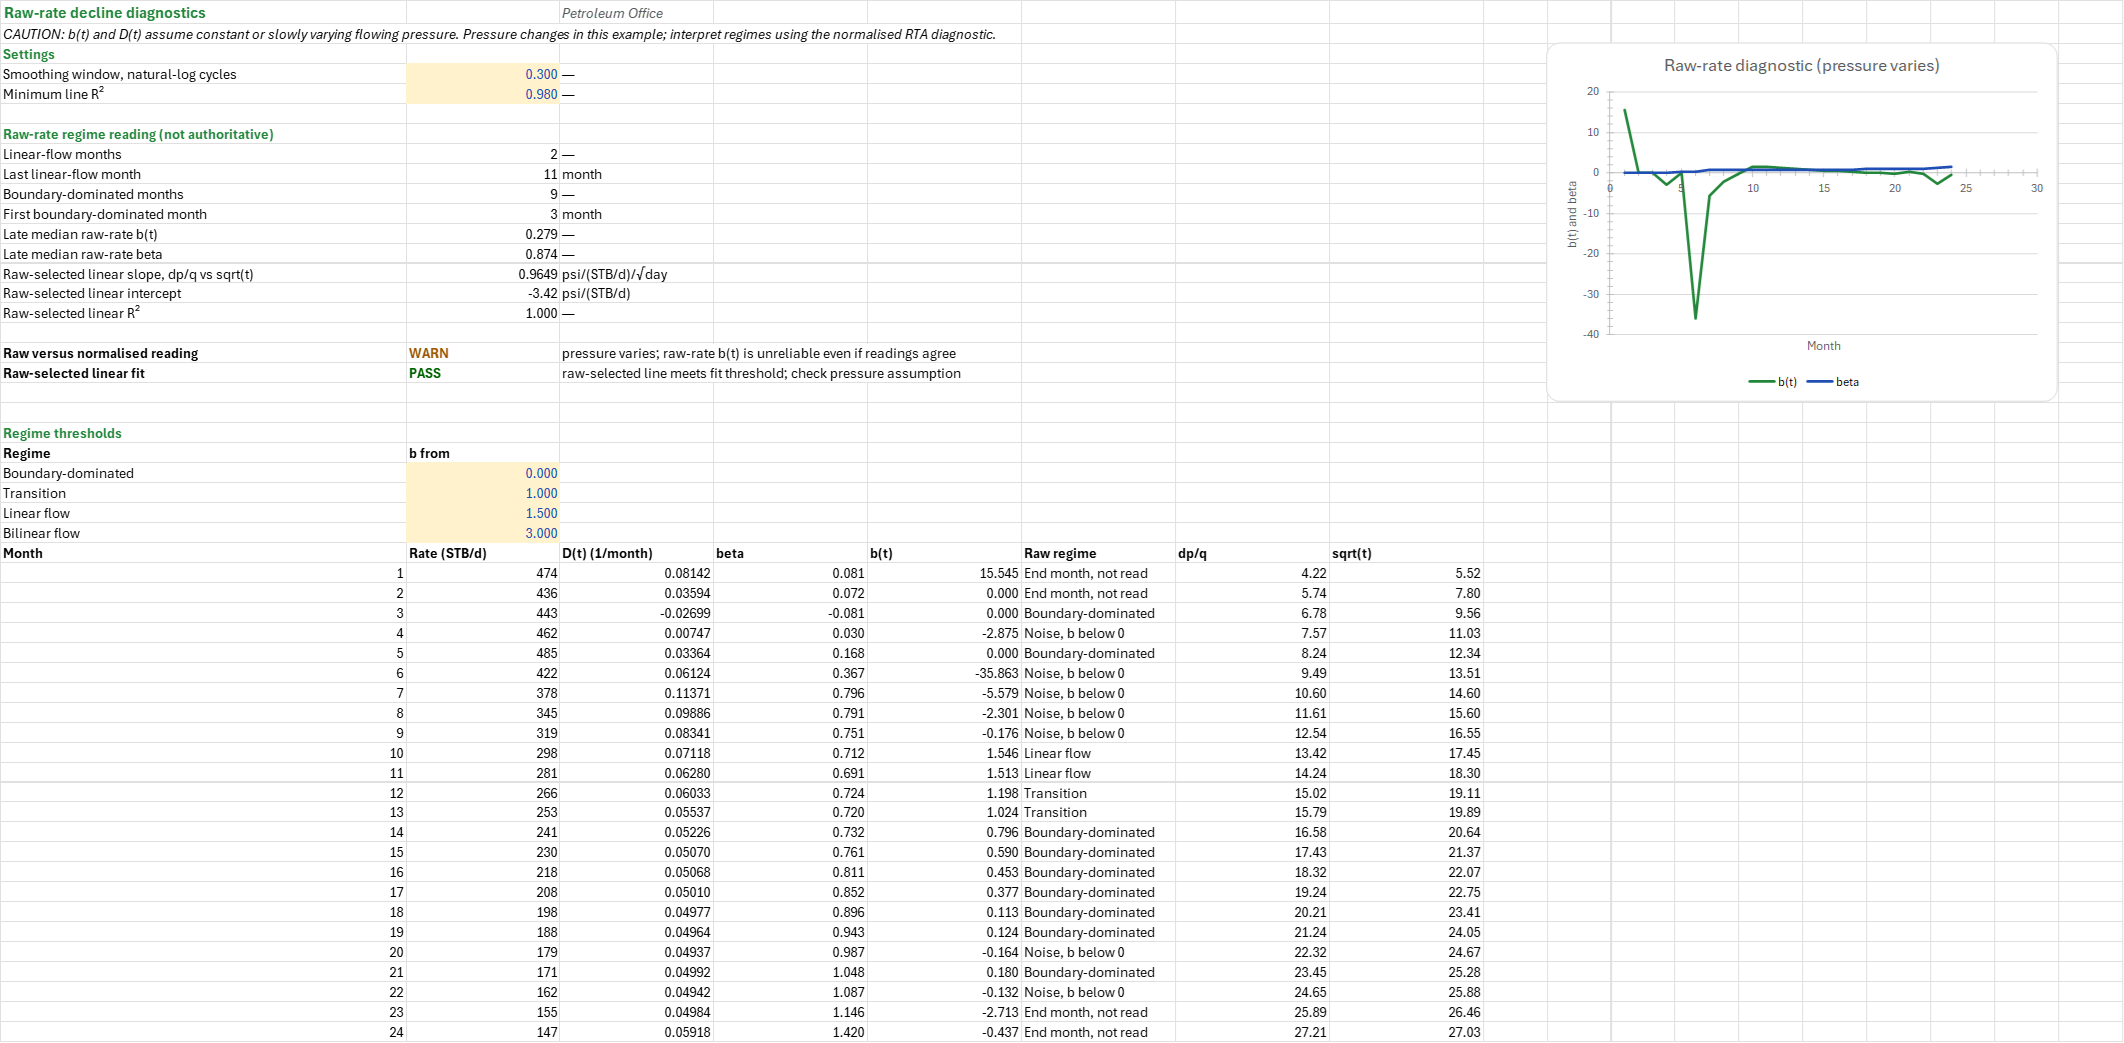
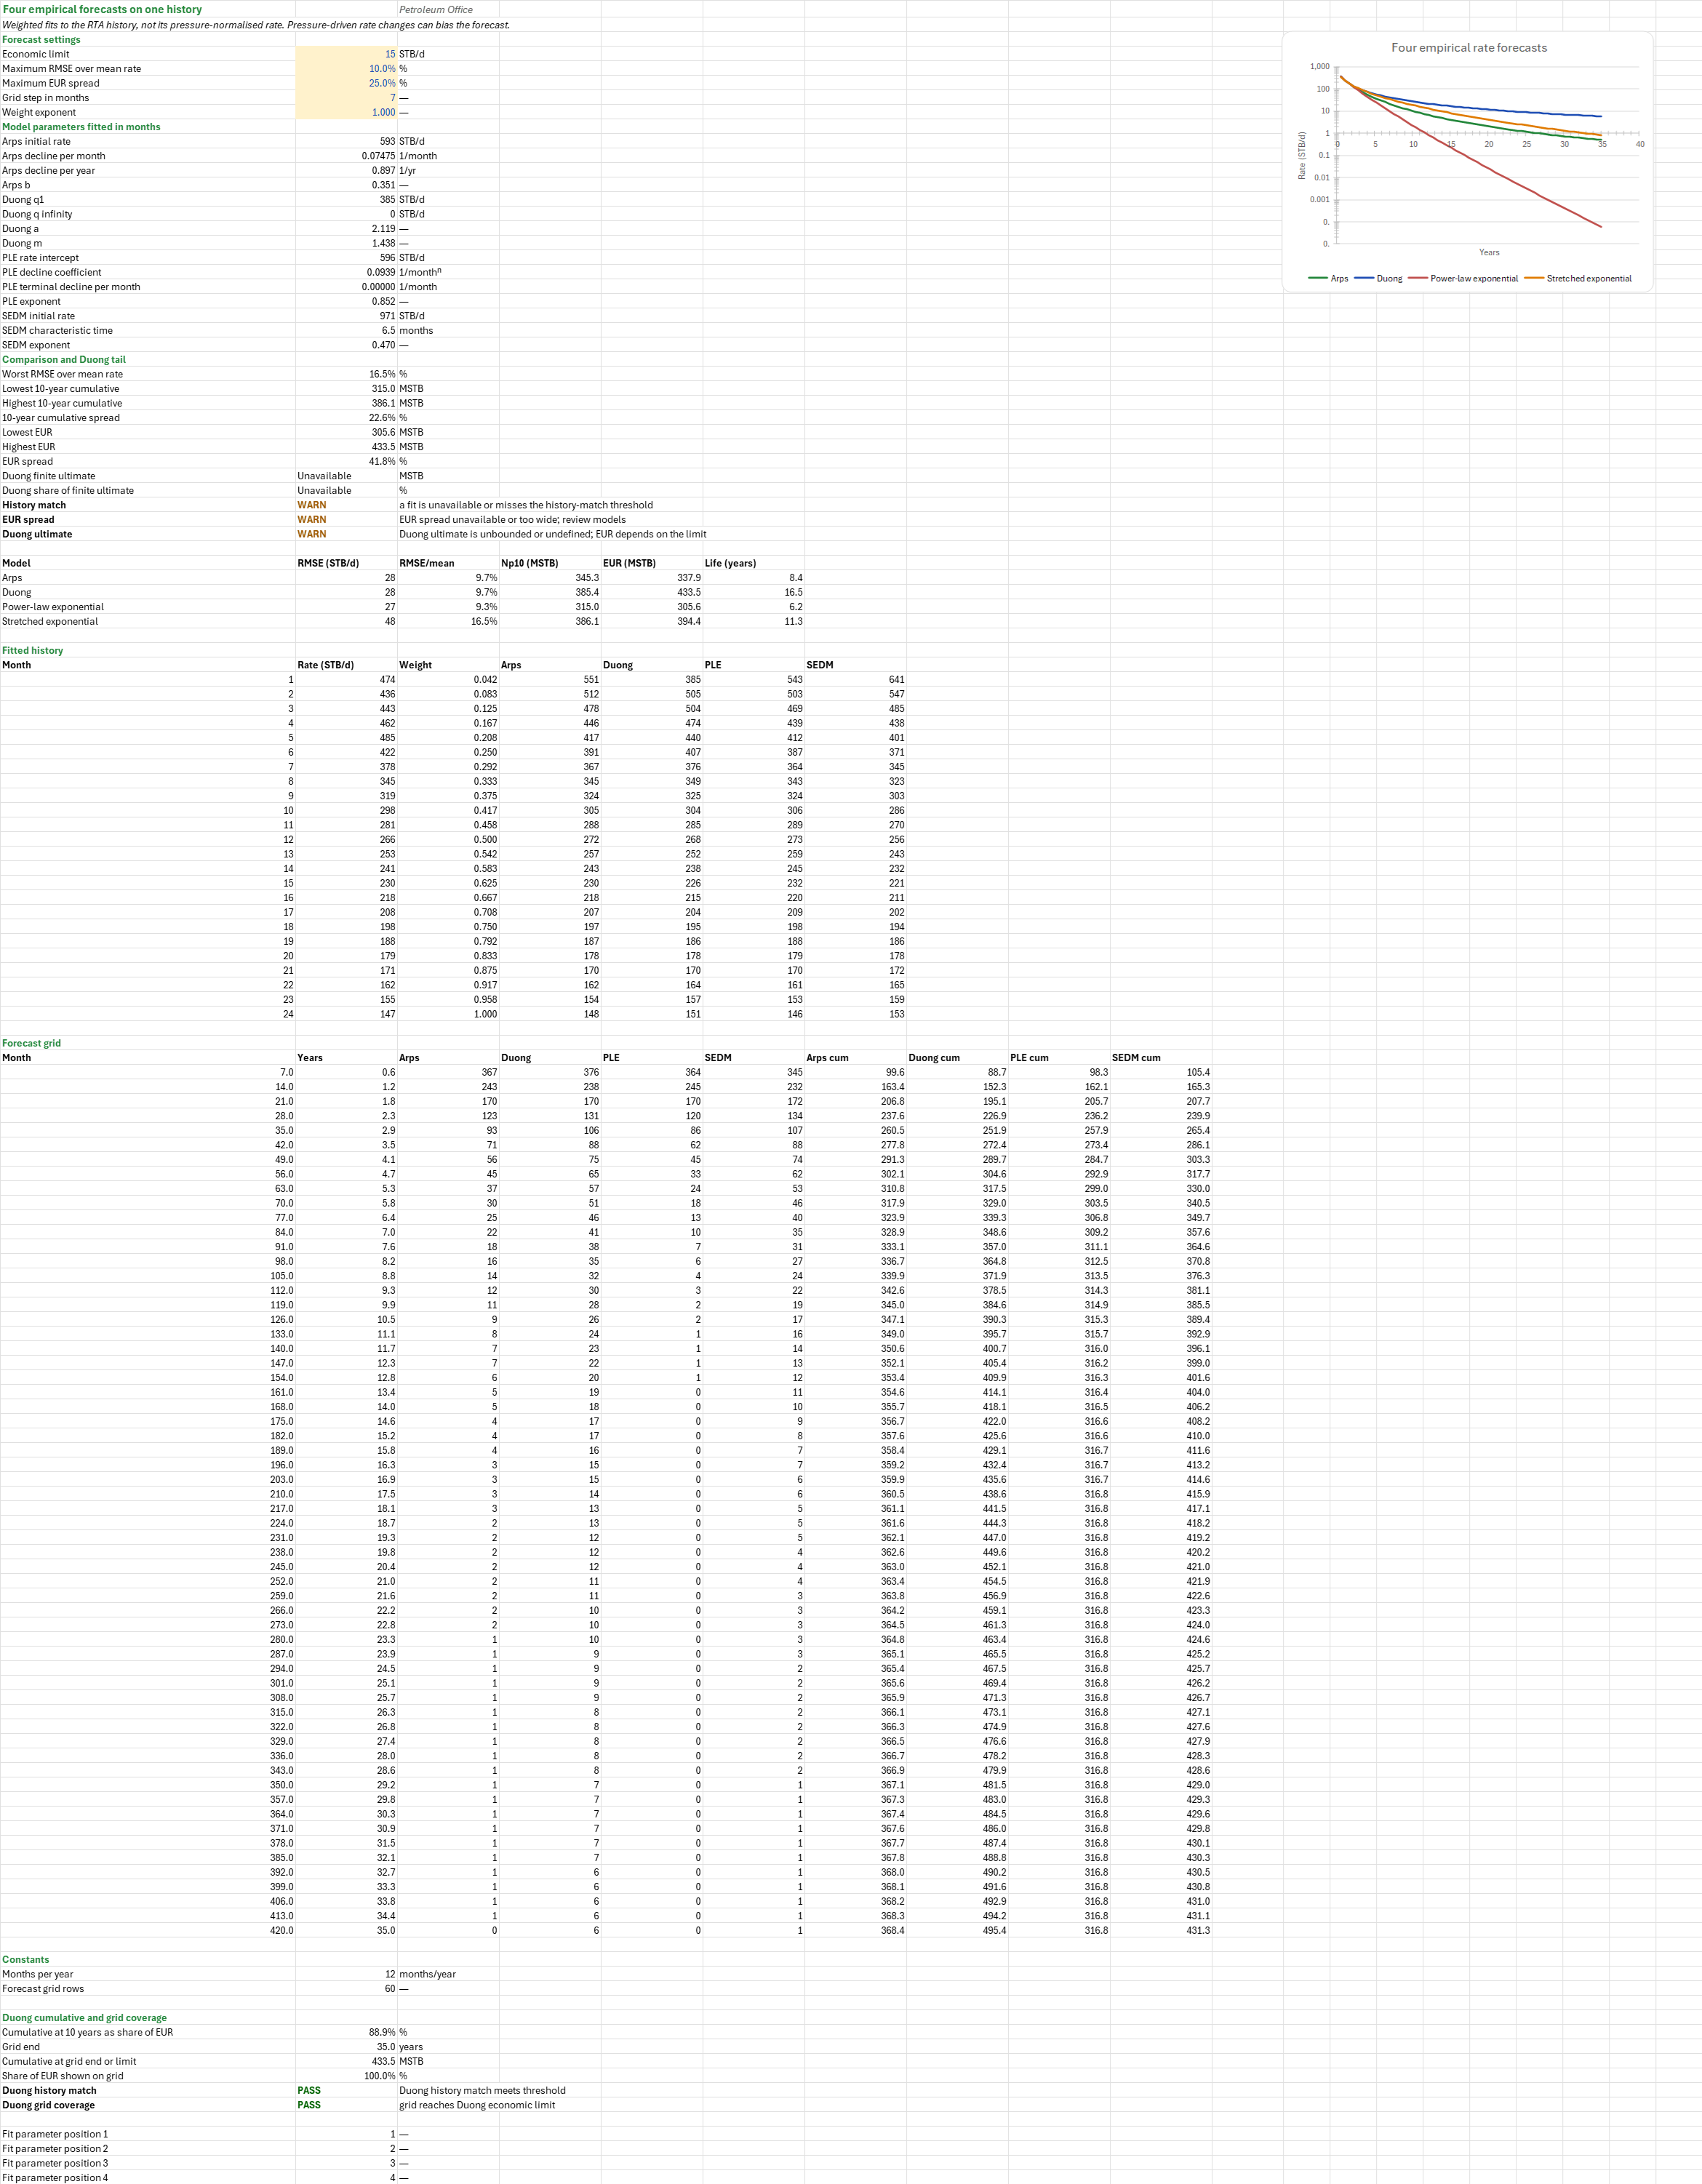
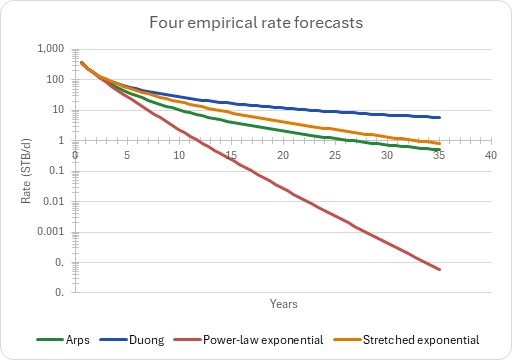
Method: Normalise rate by drawdown, calculate cumulative oil and material-balance time Np/q, then read the slope of the derivative of inverse normalised rate against material-balance time. A late slope near one suggests boundary-dominated flow. A line through those months gives contacted oil in place at constant total compressibility. Raw-rate D(t), beta and b(t) are shown separately. Four models (Arps, Duong, the power-law exponential and the stretched exponential) are fitted to the same monthly raw rates with late-time weights and forecast to one economic limit.
Example: The synthetic pressure decreases from 3,000 to 1,000 psi in the first five months; raw rate rises for several months while normalised rate falls. The underlying response was constructed using 5 MMSTB and constant compressibility. Rounded synthetic rates do not imply measured field results.
Validity
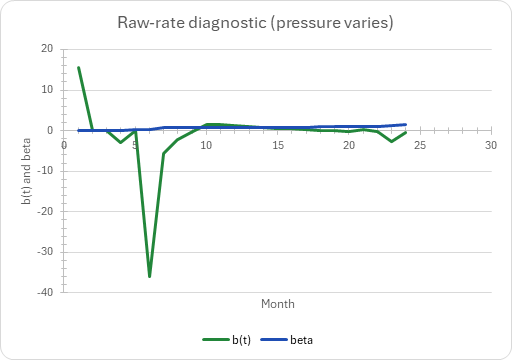
Raw-rate b(t) and D(t) assume constant or slowly varying flowing pressure; the example violates that assumption. Do not infer the physical regime solely from raw rates. Use the pressure-normalised derivative and material-balance line and investigate disagreement. Constant-compressibility oil material balance estimates contacted volume, not booked reserves. Empirical raw-rate forecasts can be biased by pressure changes and their apparent history match is not evidence of reliable extrapolation. Duong's infinite-time ultimate is finite only under the relevant parameter conditions; otherwise EUR depends on the economic limit. The workbook does not do Blasingame type-curve analysis; the add-in has no function for it.
References
- Duong, A.N. (2011). Rate-Decline Analysis for Fracture-Dominated Shale Reservoirs. SPE Reservoir Evaluation & Engineering 14(3), 377-387.
- Arps, J.J. (1945). Analysis of Decline Curves. Transactions of the AIME 160, 228-247.
Inputs
| Input | Unit | Default | Name |
|---|---|---|---|
| Monthly rate and flowing pressure | STB/d, psi | synthetic history | URF_Q, URF_Pwf |
| Initial pressure; total compressibility | psi, 1/psi | 5000, 0.000015 | URF_Pi, URF_Ct |
| Boundary-dominated derivative slope, first boundary-dominated month (0 = pick), minimum line R², minimum months on line | —, month, —, months | 0.9, 0, 0.98, 6 | URF_SlopeBdf, URF_MUser, URF_R2Min, URF_MinPts |
| Smoothing window (natural-log cycles); minimum line R² (Diagnostics) | — | 0.3, 0.98 | URD_L, URD_R2Min |
| Economic limit, maximum RMSE over mean rate, maximum EUR spread, grid step in months, weight exponent | STB/d, fraction, fraction, months, — | 15, 0.1, 0.25, 7, 1 | URM_QEcon, URM_FitMax, URM_SpreadMax, URM_Step, URM_WPow |
Sheets
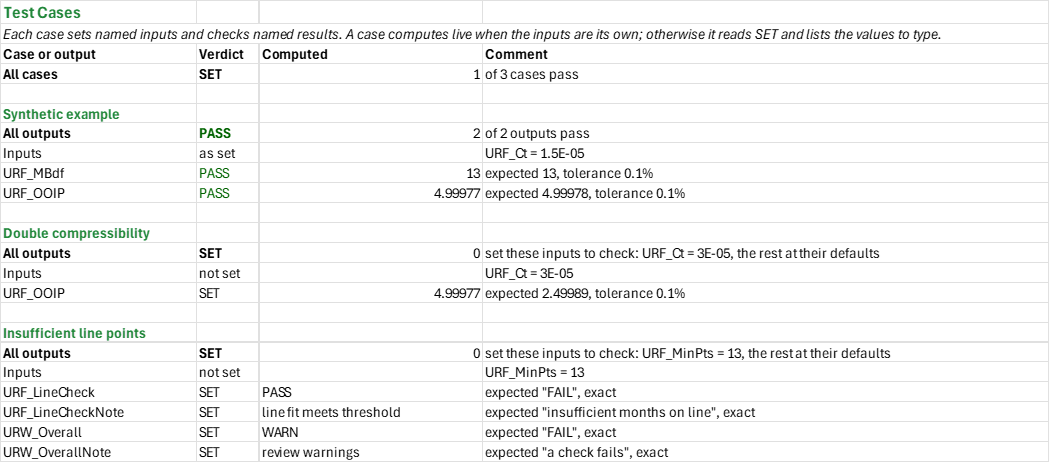
Guide— how to use the workbook, its important limitation and its assumptions.RTA History— the 24-month rate and flowing-pressure history, pressure-normalised rate, material-balance time, the derivative that picks boundary-dominated flow, and the flowing material balance line with the contacted oil in place.Diagnostics— raw-rate D(t), beta and b(t) with a regime reading against editable thresholds; pressure-sensitive and not authoritative.Forecast Models— Arps, Duong, power-law exponential and stretched-exponential fits to the history with late-time weights, their history match, EURs and spread, the Duong tail, and the forecast grid.Summary— the overall verdict, the principal results and every check.Test Cases— the worked example and other cases, with expected and computed results.
Functions used
Names (155)
| Name | Refers to | Comment |
|---|---|---|
PO.RTA.FlowingMBLAMBDA |
=LAMBDA(n_p, q, p_i, p_wf, ct, IF((ct<=0)+(SLOPE((p_i-p_wf)/q, n_p/q)<=0), NA(), 1/(SLOPE((p_i-p_wf)/q, n_p/q)*ct))) |
Contacted oil in place, STB, by flowing material balance: fits (p_i - p_wf)/q against material-balance time Np/q and returns 1/(slope*ct). Np in STB, q in STB/d, pressures in psi, ct in 1/psi; boundary-dominated points only. |
PO.RTA.NormalizedRateLAMBDA |
=LAMBDA(q, p_i, p_wf, IF((q<=0)+(p_i<=p_wf), NA(), q/(p_i-p_wf))) |
Pressure-normalized rate q/(p_i - p_wf), STB/d/psi: the rate over the drawdown from the initial reservoir pressure. Works on single values or whole columns. For gas pass pseudo-pressures m(p_i), m(p_wf). |
URD_AgreementCheck |
Diagnostics!$B$18 |
Raw versus normalised reading verdict |
URD_AgreementCheckNote |
Diagnostics!$C$18 |
Raw versus normalised reading comment |
URD_BFrom |
Diagnostics!$B$24:$B$27 |
Raw-rate b thresholds |
URD_BLate |
Diagnostics!$B$12 |
Late median raw-rate b(t) |
URD_BetaLate |
Diagnostics!$B$13 |
Late median raw-rate beta |
URD_History |
Diagnostics!$A$29:$H$52 |
Raw diagnostics against the same pressure-normalised history |
URD_Inputs |
Diagnostics!$B$4:$B$5 |
Diagnostic settings |
URD_Inv |
Diagnostics!$G$29:$G$52 |
Pressure-normalised inverse rate |
URD_L |
Diagnostics!$B$4 |
Smoothing window, natural-log cycles |
URD_LinInt |
Diagnostics!$B$15 |
Raw-selected linear intercept, psi/(STB/d) |
URD_LinR2 |
Diagnostics!$B$16 |
Raw-selected linear R² |
URD_LinSlope |
Diagnostics!$B$14 |
Raw-selected linear slope, dp/q vs sqrt(t), psi/(STB/d)/√day |
URD_LinearCheck |
Diagnostics!$B$19 |
Raw-selected linear fit verdict |
URD_LinearCheckNote |
Diagnostics!$C$19 |
Raw-selected linear fit comment |
URD_NBdf |
Diagnostics!$B$10 |
Boundary-dominated months |
URD_NLinear |
Diagnostics!$B$8 |
Linear-flow months |
URD_R2Min |
Diagnostics!$B$5 |
Minimum line R² |
URD_Regime |
Diagnostics!$F$29:$F$52 |
Raw-rate regime readings |
URD_Regimes |
Diagnostics!$A$24:$A$27 |
Raw-rate regimes |
URD_Results |
Diagnostics!$B$8:$B$19 |
Raw-rate diagnostic results and limitations |
URD_Root |
Diagnostics!$H$29:$H$52 |
Square root of elapsed days |
URD_TBdf |
Diagnostics!$B$11 |
First boundary-dominated month, month |
URD_TLinear |
Diagnostics!$B$9 |
Last linear-flow month, month |
URD_Thresholds |
Diagnostics!$A$24:$B$27 |
Raw-rate regime thresholds |
URF_Bpss |
'RTA History'!$B$19 |
Material balance intercept, psi/(STB/d) |
URF_Ct |
'RTA History'!$B$5 |
Total compressibility, 1/psi |
URF_DMo |
'RTA History'!$B$69 |
Days per month, days/month |
URF_FmbR2 |
'RTA History'!$B$21 |
Material balance R² |
URF_History |
'RTA History'!$A$43:$K$66 |
Monthly input and pressure-normalised history |
URF_Inputs |
'RTA History'!$B$4:$B$9 |
Reservoir and diagnostic settings |
URF_LinInt |
'RTA History'!$B$24 |
Transient linear-flow intercept, psi/(STB/d) |
URF_LinSlope |
'RTA History'!$B$23 |
Transient linear-flow slope, psi/(STB/d)/√day |
URF_LineCheck |
'RTA History'!$B$31 |
Material balance line verdict |
URF_LineCheckNote |
'RTA History'!$C$31 |
Material balance line comment |
URF_MBdf |
'RTA History'!$B$12 |
First boundary-dominated month used, month |
URF_MPick |
'RTA History'!$B$11 |
First month derivative slope reaches limit, month |
URF_MUser |
'RTA History'!$B$7 |
First boundary-dominated month (0 = pick), month |
URF_Million |
'RTA History'!$B$70 |
Barrels per million barrels |
URF_MinPts |
'RTA History'!$B$9 |
Minimum months on line |
URF_NBdf |
'RTA History'!$B$14 |
Months on material balance line |
URF_NCt |
'RTA History'!$B$20 |
N ct, STB/psi |
URF_NRise |
'RTA History'!$B$27 |
Months normalised rate rises |
URF_Np |
'RTA History'!$E$43:$E$66 |
Np |
URF_OOIP |
'RTA History'!$B$17 |
Contacted oil in place, MMSTB |
URF_OOIPAll |
'RTA History'!$B$18 |
Contacted oil, all months, MMSTB |
URF_Pi |
'RTA History'!$B$4 |
Initial pressure, psi |
URF_PressureCheck |
'RTA History'!$B$28 |
Drawdown verdict |
URF_PressureCheckNote |
'RTA History'!$C$28 |
Drawdown comment |
URF_PressureReady |
'RTA History'!$B$36 |
Drawdown history ready |
URF_Pwf |
'RTA History'!$C$43:$C$66 |
Pwf |
URF_Q |
'RTA History'!$B$43:$B$66 |
Q |
URF_QRise |
'RTA History'!$B$26 |
Months raw rate rises |
URF_R2Min |
'RTA History'!$B$8 |
Minimum line R² |
URF_RateCheck |
'RTA History'!$B$29 |
Rate history verdict |
URF_RateCheckNote |
'RTA History'!$C$29 |
Rate history comment |
URF_RateReady |
'RTA History'!$B$35 |
Rate history ready |
URF_RegimeCheck |
'RTA History'!$B$30 |
Normalised regime verdict |
URF_RegimeCheckNote |
'RTA History'!$C$30 |
Normalised regime comment |
URF_Results |
'RTA History'!$B$11:$B$36 |
Normalised diagnostic, material balance and checks |
URF_Rnp |
'RTA History'!$H$43:$H$66 |
Rnp |
URF_RootTc |
'RTA History'!$I$43:$I$66 |
RootTc |
URF_SlopeBdf |
'RTA History'!$B$6 |
Boundary-dominated derivative slope |
URF_SlopeLate |
'RTA History'!$B$15 |
Mean late derivative slope |
URF_T |
'RTA History'!$A$43:$A$66 |
T |
URF_Tc |
'RTA History'!$F$43:$F$66 |
Tc |
URF_TcBdf |
'RTA History'!$B$13 |
Material-balance time at pick, days |
URM_ArpsB |
'Forecast Models'!$B$13 |
Arps b |
URM_ArpsDi |
'Forecast Models'!$B$12 |
Arps decline per year, 1/yr |
URM_ArpsDiM |
'Forecast Models'!$B$11 |
Arps decline per month, 1/month |
URM_ArpsEUR |
'Forecast Models'!$E$40 |
Arps EUR |
URM_ArpsNp10 |
'Forecast Models'!$D$40 |
Arps Np10 |
URM_ArpsQi |
'Forecast Models'!$B$10 |
Arps initial rate, STB/d |
URM_ArpsRelErr |
'Forecast Models'!$C$40 |
Arps RelErr |
URM_ArpsTLim |
'Forecast Models'!$F$40 |
Arps TLim |
URM_Bound |
'Forecast Models'!$B$33 |
Duong finite ultimate, MSTB |
URM_BoundCheck |
'Forecast Models'!$B$37 |
Duong ultimate verdict |
URM_BoundCheckNote |
'Forecast Models'!$C$37 |
Duong ultimate comment |
URM_Curve |
'Forecast Models'!$A$74:$J$133 |
Forecast rate and cumulative for four models |
URM_DuongA |
'Forecast Models'!$B$16 |
Duong a |
URM_DuongEUR |
'Forecast Models'!$E$41 |
Duong EUR |
URM_DuongFitCheck |
'Forecast Models'!$B$144 |
Duong history match verdict |
URM_DuongFitCheckNote |
'Forecast Models'!$C$144 |
Duong history match comment |
URM_DuongM |
'Forecast Models'!$B$17 |
Duong m |
URM_DuongNp10 |
'Forecast Models'!$D$41 |
Duong Np10 |
URM_DuongQ1 |
'Forecast Models'!$B$14 |
Duong q1, STB/d |
URM_DuongQinf |
'Forecast Models'!$B$15 |
Duong q infinity, STB/d |
URM_DuongRelErr |
'Forecast Models'!$C$41 |
Duong RelErr |
URM_DuongTLim |
'Forecast Models'!$F$41 |
Duong TLim |
URM_Duong_Results |
'Forecast Models'!$B$140:$B$145 |
Duong cumulative shares, grid end and checks |
URM_EURHi |
'Forecast Models'!$B$31 |
Highest EUR, MSTB |
URM_EURLo |
'Forecast Models'!$B$30 |
Lowest EUR, MSTB |
URM_EURSpread |
'Forecast Models'!$B$32 |
EUR spread, % |
URM_FitCheck |
'Forecast Models'!$B$35 |
History match verdict |
URM_FitCheckNote |
'Forecast Models'!$C$35 |
History match comment |
URM_FitMax |
'Forecast Models'!$B$5 |
Maximum RMSE over mean rate, % |
URM_GridCheck |
'Forecast Models'!$B$145 |
Duong grid coverage verdict |
URM_GridCheckNote |
'Forecast Models'!$C$145 |
Duong grid coverage comment |
URM_GridEnd |
'Forecast Models'!$B$141 |
Grid end, years |
URM_HistArps |
'Forecast Models'!$D$47:$D$70 |
Arps history fit |
URM_HistDuong |
'Forecast Models'!$E$47:$E$70 |
Duong history fit |
URM_HistPLE |
'Forecast Models'!$F$47:$F$70 |
Power-law exponential history fit |
URM_HistSEDM |
'Forecast Models'!$G$47:$G$70 |
Stretched exponential history fit |
URM_History |
'Forecast Models'!$A$47:$G$70 |
Observed history, weights and the four fitted rates |
URM_Inputs |
'Forecast Models'!$B$4:$B$8 |
Economic limit, fit and spread thresholds, grid step and weight exponent |
URM_MoYr |
'Forecast Models'!$B$136 |
Months per year, months/year |
URM_Models |
'Forecast Models'!$A$40:$F$43 |
Each fitted model's mismatch, cumulative, EUR and time to the limit |
URM_Np10Hi |
'Forecast Models'!$B$28 |
Highest 10-year cumulative, MSTB |
URM_Np10Lo |
'Forecast Models'!$B$27 |
Lowest 10-year cumulative, MSTB |
URM_Np10Spread |
'Forecast Models'!$B$29 |
10-year cumulative spread, % |
URM_NpEnd |
'Forecast Models'!$B$142 |
Cumulative at grid end or limit, MSTB |
URM_PLEEUR |
'Forecast Models'!$E$42 |
Power-law exponential EUR |
URM_PLENp10 |
'Forecast Models'!$D$42 |
Power-law exponential Np10 |
URM_PLERelErr |
'Forecast Models'!$C$42 |
Power-law exponential RelErr |
URM_PLETLim |
'Forecast Models'!$F$42 |
Power-law exponential TLim |
URM_Parameter1 |
'Forecast Models'!$B$147 |
Fit parameter position 1 |
URM_Parameter2 |
'Forecast Models'!$B$148 |
Fit parameter position 2 |
URM_Parameter3 |
'Forecast Models'!$B$149 |
Fit parameter position 3 |
URM_Parameter4 |
'Forecast Models'!$B$150 |
Fit parameter position 4 |
URM_PleDi |
'Forecast Models'!$B$19 |
PLE decline coefficient, 1/monthⁿ |
URM_PleDinfM |
'Forecast Models'!$B$20 |
PLE terminal decline per month, 1/month |
URM_PleN |
'Forecast Models'!$B$21 |
PLE exponent |
URM_PleQi |
'Forecast Models'!$B$18 |
PLE rate intercept, STB/d |
URM_QEcon |
'Forecast Models'!$B$4 |
Economic limit, STB/d |
URM_Results |
'Forecast Models'!$B$10:$B$37 |
Model fits, comparison and checks |
URM_Rows |
'Forecast Models'!$B$137 |
Forecast grid rows |
URM_SEDMEUR |
'Forecast Models'!$E$43 |
Stretched exponential EUR |
URM_SEDMNp10 |
'Forecast Models'!$D$43 |
Stretched exponential Np10 |
URM_SEDMRelErr |
'Forecast Models'!$C$43 |
Stretched exponential RelErr |
URM_SEDMTLim |
'Forecast Models'!$F$43 |
Stretched exponential TLim |
URM_SedmN |
'Forecast Models'!$B$24 |
SEDM exponent |
URM_SedmQi |
'Forecast Models'!$B$22 |
SEDM initial rate, STB/d |
URM_SedmTau |
'Forecast Models'!$B$23 |
SEDM characteristic time, months |
URM_Share10 |
'Forecast Models'!$B$140 |
Cumulative at 10 years as share of EUR, % |
URM_ShareBound |
'Forecast Models'!$B$34 |
Duong share of finite ultimate, % |
URM_ShareEnd |
'Forecast Models'!$B$143 |
Share of EUR shown on grid, % |
URM_SpreadCheck |
'Forecast Models'!$B$36 |
EUR spread verdict |
URM_SpreadCheckNote |
'Forecast Models'!$C$36 |
EUR spread comment |
URM_SpreadMax |
'Forecast Models'!$B$6 |
Maximum EUR spread, % |
URM_Step |
'Forecast Models'!$B$7 |
Grid step in months |
URM_W |
'Forecast Models'!$C$47:$C$70 |
Late-time weights |
URM_WPow |
'Forecast Models'!$B$8 |
Weight exponent |
URM_WorstFit |
'Forecast Models'!$B$26 |
Worst RMSE over mean rate, % |
URW_BLate |
Summary!$B$9 |
Raw-rate late b(t), pressure-sensitive |
URW_Checks |
Summary!$B$16:$B$26 |
Every named check, read from its sheet |
URW_EURHi |
Summary!$B$11 |
Highest forecast EUR, MSTB |
URW_EURLo |
Summary!$B$10 |
Lowest forecast EUR, MSTB |
URW_MBdf |
Summary!$B$7 |
Normalised boundary-dominated month, month |
URW_OOIP |
Summary!$B$8 |
Contacted oil in place, MMSTB |
URW_Overall |
Summary!$B$4 |
Overall verdict verdict |
URW_OverallNote |
Summary!$C$4 |
Overall verdict comment |
URW_Results |
Summary!$B$7:$B$11 |
Material balance and forecast results |
URW_Verdict |
Summary!$B$4 |
Overall verdict |
URW_VerdictNote |
Summary!$C$4 |
Overall comment |
Details
| Opens in | Needs the Petroleum Office add-in: its PO functions show #NAME? without it once Excel recalculates. Needs Microsoft 365 or Excel 2024: it uses functions Excel 2016 doesn't have, such as named LAMBDAs, which show #NAME? there. |
| File | UnconventionalRta.xlsx, 82 KB |
| Category | Production |
| For agents and tools | Descriptor (.md) |